By
Lee Tokouzis
Director of OperationsGreece Sotheby’s International Realty publishes a semi-annual review of the Greek luxury residential market. This summary covers 1 January to 30 June 2026 (H1 2026). It compares that period with the same window in 2025 and with a five-year average for 2021 to 2025. The figures come from the firm’s own buyer enquiry and listing records. The full report is available here: The State of the Greek Luxury Property Market H1 2026.
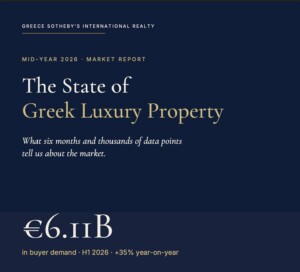
Key figures for H1 2026
- Buyer enquiry volume: €6.11 billion, up 35% on H1 2025 (€4.51 billion) and 19% above the five-year average (€5.12 billion).
- Median enquiry value: €2.95 million, up 28% from €2.30 million in 2025.
- Share of enquiry volume from properties above €5 million: 70%, with volume in that tier up 45% year on year.
- Median time from listing to signed agreement: about 238 days.
- Non-domiciled resident buyers: 29% of 2025 transaction volume, and 53% of that segment is British.
- Median asking price, Athens Riviera active luxury listings: €10,213 per square metre.
What does the €6.11 billion figure measure?
The €6.11 billion is enquiry volume: the total indicative value of the properties that buyers enquired about during the period. It measures buyer interest at the start of the buyer journey, before viewings, agreements or completed sales.
Where a listing price is unpublished (price on application), the report weights the enquiry at 68% of its nominal value. This reflects how buyers respond to listings without a stated price. Repeat enquiries from the same buyer count in full for the first two, then at 60% for the third, 40% for the fourth, and 20% for each one after. The same method applies to every year compared, so the comparisons are like for like.
The €650 million figure that appears on the report cover is the cumulative gross value of properties the firm has handled since it was founded. The report publishes enquiry volume at period level and transaction value cumulatively.
How did the Iran conflict affect demand?
The conflict that began on 1 March 2026 produced the only measurable demand disruption of the half-year. Enquiry patterns moved through four phases, compared with the same calendar windows in 2025:
| Window | Daily enquiries vs 2025 | Enquiry value vs 2025 |
|---|---|---|
| Pre-war, 1 Jan to 28 Feb | +31% | Growth established before the conflict |
| Shock, 1 to 20 Mar | −5% | +36% |
| Partial recovery, 21 Mar to 9 Apr | +12% | +49% |
| Decisive rebound, 10 to 30 Apr | +47% | +71% |
| Sustained demand, May to June | +5% to +31% | June value +64% |
In practical terms, buyer interest was disrupted for about forty days. For the first twenty of those days, the number of enquiries fell slightly while the value of enquiries kept growing. From mid-April the market moved above its pre-war pace and has stayed there.
Are prices holding?
The asking prices below cover more than 400 active luxury listings across the firm’s principal Greek markets at mid-year 2026. They are current asking prices, after any price revisions made during each listing’s marketing period. Transaction prices are a separate measure.
| Region | Median €/m² | Listing range €/m² |
|---|---|---|
| Mykonos | 10,938 | 2,481 to 24,688 |
| Athens Riviera (44 listings) | 10,213 | 3,381 to 26,848 |
| Athens Centre | 9,489 | 3,766 to 20,000 |
| Lefkada | 9,130 | 5,474 to 17,885 |
| Paros | 9,028 | 4,748 to 21,661 |
| Corfu (70 listings) | 8,716 | 2,727 to 26,820 |
| Tinos | 7,729 | 3,943 to 11,513 |
| Zakynthos | 7,123 | 3,441 to 14,000 |
| Kea | 7,015 | 4,181 to 15,000 |
| Kefalonia | 6,222 | 3,333 to 8,429 |
| Crete | 6,013 | 2,614 to 13,158 |
| Athens North | 5,273 | 2,493 to 20,022 |
| Total active inventory | 8,333 | 1,835 to 40,000 |
Median asking prices rise with the price tier:
| Price tier | Median €/m² | Average €/m² |
|---|---|---|
| Below €2 million | 6,438 | 6,785 |
| €2 million to €5 million | 8,824 | 9,163 |
| Above €5 million | 12,355 | 13,569 |
Price revisions point in one direction. Among 25 active listings with both a 2025 and a 2026 asking price that differ, 72% of revisions were downward, with a median reduction of about 8%. The reductions appear across every price tier, from below €2 million to over €20 million.
Time to sale also varies widely. The median time from publication to signed agreement across completed sales is about 238 days, or roughly eight months. Of completed sales, 41% closed within six months of listing, a further 20% within twelve months, and 39% took more than a year. The report’s conclusion is that realistically priced homes move at a natural pace, while homes held at exploratory prices for six or twelve months without serious offers tend to be treated by the market as unsold rather than undervalued.
Who is buying?
| Country | H1 2026 share | H1 2025 share | Change in volume |
|---|---|---|---|
| Greece (domestic) | 18.8% | 21.8% | +17% |
| United Kingdom | 17.4% | 14.7% | +60% |
| United States | 14.5% | 16.9% | +16% |
| France | 6.3% | 5.8% | +45% |
| Australia | 4.2% | 3.5% | +60% |
| Germany | 3.3% | 4.6% | −1% |
| Switzerland | 2.9% | 3.1% | +29% |
| Canada | 2.4% | 2.1% | +54% |
| Netherlands | 2.2% | 1.0% | +199% |
| United Arab Emirates | 2.2% | 3.6% | −20% |
| Belgium | 1.9% | 1.3% | +101% |
| South Africa | 1.8% | 0.7% | +264% |
| Spain | 1.8% | 0.4% | +470% |
Greek domestic buyers are the largest single national group, at 18.8% of enquiries, against a five-year average of 15.3%. The UK share rose to 17.4%, above its five-year average of 15.1%. The report links this recovery to the UK’s abolition of its non-dom regime, effective April 2025. The US share of 14.5% sits below its five-year average of 21.8%. The UAE share has settled at 2.2%, down from its 2024 and 2025 peaks, and it remains concentrated in Athens Riviera ultra-luxury property. The fastest growth came from the Netherlands, Spain, Belgium and South Africa, from smaller bases.
The non-domiciled resident segment
Non-domiciled resident buyers first appear in the firm’s records in 2024. Their share has grown since:
| Year | Share of deals | Share of transaction volume |
|---|---|---|
| 2020 to 2023 | 0% | 0% |
| 2024 | 17% | 14% |
| 2025 | 21% | 29% |
| H1 2026 | 14% | 10% |
Greece introduced its non-dom programme in 2020. It offers qualifying new tax residents a €100,000 annual flat-tax election on foreign-source income for fifteen years. Between 2024 and 2026, 53% of non-dom transactions in the firm’s records involved UK buyers and 12% involved US buyers. The report reads this concentration as consistent with relocation from London after the UK regime was abolished. The H1 2026 figure is a mid-year snapshot; a like-for-like comparison with earlier years becomes possible with the full-year 2026 figures.
Athens Riviera: the defining structural development
The convergence of the Hellinikon megaproject, the Apollo Hills branded residences programme and the wider regeneration of the southern Attica coast has created a concentrated luxury submarket. The Athens Riviera is the category the report identifies as defining the current Greek luxury cycle.
Active luxury listings on the Athens Riviera have a median asking price of about €10,200 per square metre, with branded off-plan product priced materially higher. The firm’s enquiries through the Apollo Hills developer channel grew from a negligible presence in 2023 to a significant share of qualified enquiries by H1 2026. The report also notes that most Athens Riviera off-plan transactions clear the €800,000 threshold for a Greek residence permit.
The report describes the buyer profile as distinct from the traditional island buyer. Athens Riviera buyers generally prioritise infrastructure, brand, and proximity to the airport, international schools and amenities. Island buyers more often prioritise lifestyle and the character of the setting. The report’s view is that a complete analysis of the Greek luxury market covers both.
Greek domestic buyers
Greek buyers accounted for 18.8% of enquiries in H1 2026, the largest single national share. The report identifies three groups within this segment: Athens-based ultra-high-net-worth households diversifying their property holdings, shipping and entrepreneurial families who often buy through advisers, and the repatriating Greek diaspora buying for remote work, retirement or eventual return. The report also finds that Greek buyers move from enquiry to viewing to agreement more quickly than international buyers, because they already know the legal process.
The €5 million-plus tier anchors the market
Properties above €5 million have accounted for between 66% and 74% of enquiry volume in each H1 period the report measures:
| Period | Below €2M | €2M to €5M | Above €5M |
|---|---|---|---|
| H1 2024 (peak year) | 9% | 17% | 74% |
| H1 2025 (moderation) | 8% | 26% | 66% |
| H1 2026 | 7% | 23% | 70% |
Enquiry volume in the €5 million-plus tier grew 45% year on year in H1 2026, about two and a half times the 18% growth in the below-€2 million tier. The report describes this tier as the market’s structural anchor. Buyers at this level are less sensitive to interest rates and to the wider economic cycle than buyers below it.
The economic backdrop
In March 2026, Moody’s upgraded Greece from Ba1 to Baa3. With this upgrade, all five major rating agencies rate Greece investment grade for the first time since 2010. The report notes that Greece’s debt-to-GDP ratio has fallen by about fifty percentage points from its 2020 peak, and it cites a projection of 140.6% by end-2026, down from 156.1% at end-2024.
On 11 June 2026 the European Central Bank raised its deposit facility rate by 25 basis points to 2.25%. This was its first increase in the post-2023 cycle, reflecting inflation linked to the Iran conflict and to disruption to oil shipments through the Strait of Hormuz. Most Greek luxury buyers purchase in cash or with low leverage, so the direct effect on them is limited. The indirect effects, through European wealth creation and buyers’ purchasing power in 2027, are more significant.
The euro traded in a range of about $1.10 to $1.17 through H1 2026. This supported US buyers, who accounted for 15% of enquiries.
What to watch in H2 2026
The report identifies five variables for the second half:
- Athens Riviera deliveries. The pace at which branded developments complete will determine whether H1 demand becomes closed sales in 2026 or moves into 2027.
- The UAE buyer trajectory. Whether the normalisation after 2024 and 2025 is temporary or lasting.
- The non-dom segment. The report expects its share of transaction volume to stay at or above the 2025 level of 29% through 2026 and 2027.
- The ECB rate path. A sustained tightening cycle would affect mass-luxury and mid-luxury buyers more than the €5 million-plus tier.
- Pricing discipline. Realistically priced properties are expected to keep selling, while properties priced at exploratory levels are expected to accumulate on the market.
How enquiries become sales
Enquiry volume is the top of the buyer journey. The report describes typical conversion ratios for the luxury Greek market, based on rolling multi-year figures from 2017. These ratios are illustrative rather than forecasts:
- Enquiry to property viewing: about 12%
- Viewing to signed agreement (LOI): about 11%
- Signed agreement to closed transaction: about 78%, with about 22% of agreements falling through, usually because of financing, legal due diligence or buyer reconsideration
Taken together, the blended conversion from enquiry to closed sale is about 1%. Because a luxury sale usually takes months, enquiries received in January often become agreements in April or May at the earliest. The €6.11 billion enquired about in H1 2026 will therefore produce signed agreements through the end of 2026 and into early 2027.
Frequently asked questions
How much did Greek luxury property demand grow in H1 2026?
Enquiry volume reached €6.11 billion, up 35% on H1 2025 and 19% above the five-year average. This measures buyer interest, with signed sales following over the subsequent months.
What are the median asking prices per square metre in Greek luxury property?
Across all active luxury listings the median is €8,333 per square metre. Among regions with more than ten listings, Mykonos (€10,938) and Athens Riviera (€10,213) have the highest medians.
How long does it take to sell a luxury property in Greece?
The median time from publication to signed agreement is about 238 days. Forty-one percent of sales closed within six months and 39% took more than a year.
Who is buying Greek luxury property?
Greek domestic buyers account for 18.8% of enquiries, UK buyers for 17.4% and US buyers for 14.5%. Non-domiciled resident buyers made up 29% of 2025 transaction volume, and 53% of that segment is British.
Did the Iran conflict affect the Greek luxury market?
Briefly. Enquiry counts fell 5% year on year in the first twenty days after 1 March 2026, while enquiry value still rose 36%. From mid-April demand moved above its pre-war pace, and June value rose 64% year on year.
What does the data suggest for sellers in H2 2026?
Realistically priced properties continue to sell at a natural pace. In the sample of 25 listings with a tracked price change, 72% of revisions were downward, with a median reduction of about 8%.
Methodology and definitions
- Period: 1 January to 30 June 2026, compared with the same calendar window in 2025 and with the 2021 to 2025 average.
- Enquiry volume: the indicative value of buyer enquiries, weighted for price-on-application listings and for repeat enquiries from the same buyer.
- Asking prices: current listing prices per square metre across more than 400 active luxury listings, after revisions.
- Days on market: measured from first publication to signed agreement, on completed sales.
- Price revisions: based on 25 active listings with differing 2025 and 2026 asking prices.
- Conversion ratios: illustrative rolling ratios from 2017.
- Tracked value: the €650 million figure is the cumulative gross value handled since the firm was founded.
The full report, thirteen sections covering demand, pricing, buyer origins, the conversion funnel and the macroeconomic context, is available here: The State of the Greek Luxury Property Market H1 2026. Questions about the data can be sent to [email protected].